Moving out on your own and starting your first full-time job is an exciting step toward independence. You finally get to make your own decisions, manage your money, and build a life that feels like yours. But there is one important part of adult life that can take some getting used to: paying bills on time.
When you live independently, rent, electricity, internet, and other monthly expenses become your responsibility. Forgetting a payment can lead to late fees, service interruptions, or unnecessary stress. Fortunately, online bill payment makes managing these expenses much easier.
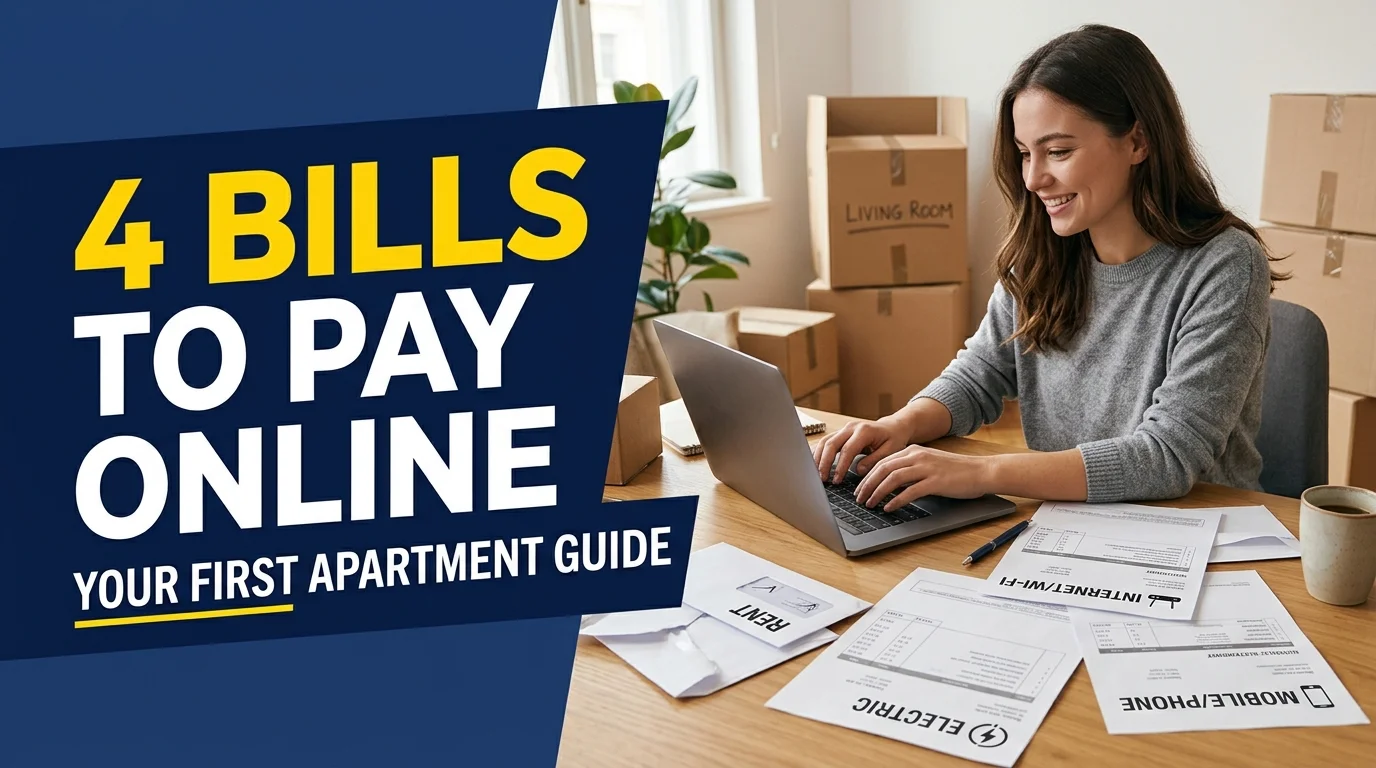
Picture yourself moving out on your own or maybe with a roommate, working your first full-time job. You will probably have several people or companies you need to pay regularly. At least four common examples are your landlord, electric company, internet provider, and phone service provider.
Let’s look at how these payments work, why online bill pay is useful, and how you can manage your money responsibly while starting your independent life.
What Is Online Bill Pay?
Online bill pay is a service that allows you to pay bills electronically instead of writing checks, mailing payments, or visiting a payment office.
You can usually make payments through your bank’s website or mobile app, or directly through a company’s website or app. Depending on the service, you may be able to schedule one-time payments, set up automatic recurring payments, and review your payment history.
For someone starting a full-time job, online bill pay can save time and make monthly budgeting more manageable.
For example, imagine you receive your paycheck every other Friday. You could schedule your rent payment around payday, arrange automatic payments for your internet bill, and receive reminders when your phone bill is due.
The key is to choose a payment method that fits your budget and check your account regularly.
Picture Yourself Moving Out on Your Own: 4+ People or Companies You Should Pay Regularly Using Online Bill Pay
Here are four essential examples of people or companies you might pay when living on your own or sharing an apartment with a roommate.
1. Your Landlord or Property Management Company
Rent is often one of the largest monthly expenses for someone living independently.
If you rent an apartment, house, or room, you will generally need to pay your landlord or property management company every month. Many landlords accept online payments through a tenant portal, bank transfer, or an approved electronic payment service.
Why you might use online bill pay:
- You can schedule rent payments in advance.
- You can keep a digital record of your transactions.
- You can reduce the risk of forgetting the due date.
- You may avoid the inconvenience of delivering a check in person.
For example, suppose your monthly rent is $1,000 and it is due on the first of every month. You could schedule the payment a few days early, allowing enough time for processing.
Before setting up a payment, confirm the landlord’s accepted payment methods, processing times, and any transaction fees. Keep enough money in your account to cover the full amount.
2. Your Electric or Utility Company
Electricity is another regular expense you will likely encounter when moving into your first apartment.
Depending on where you live, you may also need to pay for natural gas, water, sewer service, or trash collection. These bills may come from separate companies or be included in your rent.
Online bill payment lets you pay utility bills through a provider’s website, mobile app, or your bank’s bill payment service.
Benefits of paying utility bills online include:
- Convenient access to your bill and payment history.
- Payment reminders and electronic statements.
- The ability to schedule payments before the due date.
- Less paperwork to manage each month.
For instance, if your electricity bill is $75 for the month, you can review the amount, check your account balance, and schedule payment before the deadline.
Utility bills can change depending on the season and how much electricity you use. It is a good idea to review each bill instead of assuming the amount will always stay the same.
3. Your Internet Service Provider
Internet service has become an important part of everyday life. You may need it for remote work, online classes, job applications, entertainment, and staying connected with family and friends.
When you move into your own place, you may sign up with an internet service provider and agree to pay a monthly fee.
Most major providers offer online account management, where customers can view statements, pay bills, and manage recurring payments.
Why online bill pay makes sense for internet service:
- You can pay without calling customer service.
- You can check whether your payment has been received.
- You can manage your bill from your phone or computer.
- You can set reminders to avoid missing a payment.
Imagine you work a remote full-time job and rely on a stable internet connection for meetings and daily tasks. Paying your internet bill on time helps you avoid the inconvenience of a potential service interruption.
Before choosing a provider, compare monthly prices, installation charges, equipment fees, contract terms, and any promotional rates that may expire.
4. Your Cell Phone Service Provider
Your cell phone is another expense you may need to manage every month.
You might use your phone for work calls, navigation, banking, communication, and two-factor authentication when signing in to important accounts.
If you have a monthly phone plan, you will typically receive a bill from your wireless provider. You can often pay it online or enable automatic payments.
Advantages of online phone bill payments include:
- Quick payments through a website or mobile app.
- Access to billing details and past transactions.
- Notifications about upcoming due dates.
- Convenient management of recurring expenses.
For example, suppose your phone plan costs $60 per month. You can include that amount in your monthly budget and schedule payment after your paycheck arrives.
If you are trying to reduce expenses, compare your current plan with less expensive options. A cheaper plan may offer enough data and calling features for your needs.
Other People or Companies You May Need to Pay
Although the four examples above are common, your actual bills will depend on your living arrangements, transportation needs, and financial responsibilities.
Here are several other possible payments.
5. Your Student Loan Servicer
If you borrowed money to attend college or complete professional training, you may need to make regular student loan payments.
Your loan servicer may provide an online account where you can review your balance, check payment dates, and choose an available payment method.
If you have federal student loans, review the official information at StudentAid.gov before selecting a repayment plan.
6. Your Credit Card Company
If you use a credit card for groceries, gas, or other purchases, you will need to pay at least the required amount by the due date to keep the account in good standing.
Paying your full statement balance by the due date generally helps you avoid interest on purchases when your card has a grace period and you qualify for it.
Online bill pay can help you schedule payments and monitor your transactions. However, make sure you have enough money available in your bank account when the payment is processed.
7. Your Car Loan Lender or Auto Insurance Company
If you own a car, you may have monthly loan payments and recurring insurance premiums.
Your lender or insurer may allow you to set up automatic payments through its website or app. Check your statements regularly because insurance premiums, loan terms, and payment dates can differ.
If you use public transportation instead, you might have fewer transportation-related bills to manage.
How to Set Up Online Bill Payment Safely
Online bill payment is convenient, but it is important to use it carefully. A few simple habits can help you avoid missed payments, unexpected fees, and fraud.
- Use official websites and apps. Access your bank or service provider directly rather than clicking unfamiliar links in text messages or emails.
- Confirm the payment details. Check the recipient, account number, amount, and due date before sending money.
- Keep enough money in your account. Automatic payments can cause overdraft fees or failed payments if your balance is too low.
- Schedule payments with enough time. Bank bill pay and direct payments to companies may have different processing times.
- Save your confirmation numbers. Digital receipts can help you resolve billing disputes.
- Review your bank statements. Check for duplicate charges, incorrect amounts, or transactions you do not recognize.
- Protect your login information. Use strong, unique passwords and enable multifactor authentication when available.
You should also understand the difference between automatic payments and scheduled bank bill payments. An automatic payment set up with a company may withdraw money directly from your bank account, while a bank bill pay service may send an electronic payment or, in some cases, a paper check.
Read the terms of the service you choose so you know how payments are processed.
How to Budget for Bills When You Start Your First Full-Time Job
Getting your first full-time job can feel like a major financial milestone. Still, your paycheck may need to cover more expenses than you initially expect.
Before spending your money on entertainment or shopping, identify your regular bills and set aside enough to cover them.
Step 1: Calculate Your Take-Home Pay
Your take-home pay is the money you receive after taxes and other payroll deductions.
For example, if your monthly take-home pay is $2,800, use that figure when planning your budget rather than your gross salary.
Step 2: List Your Monthly Bills
Write down your rent, utilities, internet, phone, transportation, insurance, debt payments, and other recurring expenses.
Include variable expenses, such as electricity, and leave room for occasional costs, such as car repairs or medical bills.
Step 3: Choose Your Payment Dates
Review each bill’s due date and compare it with your payday schedule.
If possible, schedule payments so they arrive before their deadlines. Avoid scheduling a payment simply because you expect to receive a paycheck on the same day, since deposits and payment processing can sometimes be delayed.
Step 4: Build an Emergency Fund
Even a small emergency fund can help cover an unexpected bill, a necessary repair, or a temporary reduction in income.
Start with an amount that fits your budget and gradually increase it as your finances improve.
Step 5: Review Your Budget Every Month
Your expenses may change when your lease renews, your internet promotion expires, or your insurance premium increases.
Reviewing your spending every month helps you catch changes early and make adjustments before they create financial problems.
What If You Live With a Roommate?
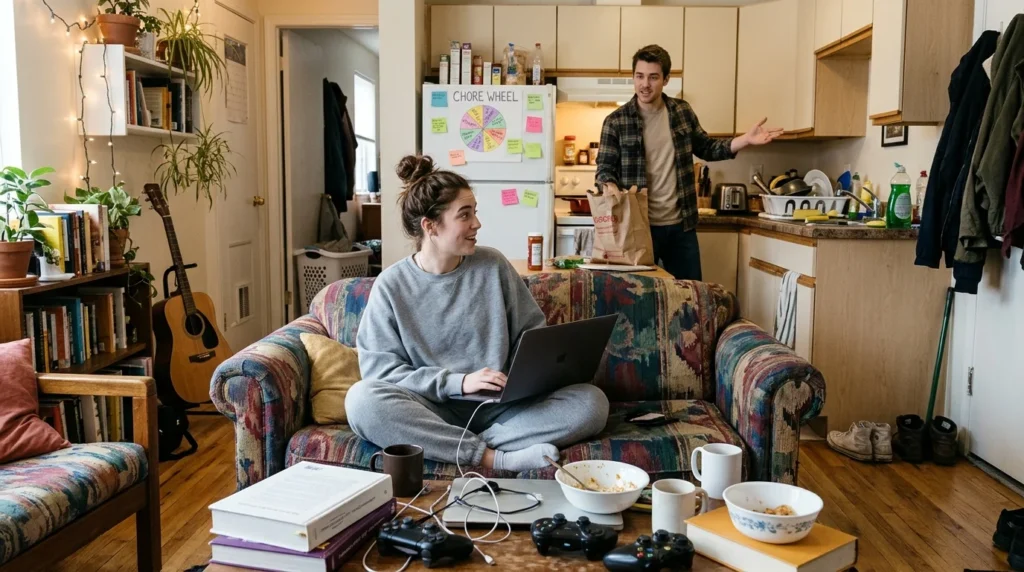
Sharing an apartment can make housing more affordable, but it also requires clear communication about shared bills.
For example, you and your roommate might split rent, electricity, and internet costs equally. One person may pay the full internet bill and receive the other person’s share through an agreed-upon payment method.
To avoid misunderstandings:
- Agree on how shared bills will be divided.
- Set a clear deadline for each person’s contribution.
- Keep receipts and payment records.
- Decide who will contact the provider if there is a billing issue.
- Discuss how you will handle unexpected charges.
Do not assume that a roommate’s promise to contribute removes your legal responsibility under a lease or service agreement. Check the contract to understand who is responsible for each payment.
Online Bill Pay vs. Manual Payments: Which Is Better?
Online bill payment can save time, but the best option depends on your needs.
| Feature | Online bill pay | Manual payments |
|---|---|---|
| Convenience | Pay from a website or app | Requires you to initiate each payment |
| Reminders | Often available | You may need to create your own reminders |
| Payment records | Usually available digitally | Records may be spread across receipts and statements |
| Scheduling | Often supports scheduled or recurring payments | Depends on the payment method |
| Risk to watch | Insufficient funds or incorrect automatic withdrawals | Forgetting a due date or entering payment details incorrectly |
For most people with regular monthly bills, online bill pay is a practical option. You can automate predictable expenses while continuing to review each bill yourself.
That balance is important. Automation should make bill management easier, not replace your responsibility to monitor your finances.
Trusted Resources for Managing Your Bills
If you are learning how to handle your money independently, these established resources can help:
- Consumer Financial Protection Bureau (CFPB): Visit consumerfinance.gov for consumer financial education and guidance on managing money, accounts, and credit.
- Federal Trade Commission (FTC): Visit consumer.ftc.gov for practical information about avoiding scams and protecting your personal information.
- Federal Student Aid: Visit studentaid.gov for official information about federal student loans and repayment options.
These resources can help you make informed decisions as you take responsibility for your own household expenses.
FAQs
1. What are four examples of people or companies you might pay regularly using online bill pay?
Four common examples are your landlord or property management company, electric utility provider, internet service provider, and cell phone service provider. Depending on your circumstances, you may also pay a student loan servicer, credit card company, or car insurance provider.
2. Is online bill payment safe?
Online bill payment can be safe when you use trusted payment services, verify the recipient, protect your login information, and monitor your transactions. No payment method is completely risk-free, so avoid unfamiliar links and report suspicious transactions promptly.
3. Can I schedule my bills to be paid automatically?
Yes. Many banks and service providers allow customers to schedule one-time or recurring payments. Before enabling automatic payments, check the due date, processing time, payment amount, and available account balance.
4. What bills should I pay first when I get my first full-time job?
Start with essential expenses such as housing, utilities, food, transportation, and necessary insurance. Then account for debt payments, savings, and other recurring expenses. Your priorities may vary based on your lease, loan agreements, and personal circumstances.
5. Is online bill pay free?
Some banks include bill payment services at no additional charge, while certain companies or third-party payment providers may charge processing fees. Check the terms before choosing a payment method, especially if you plan to make recurring payments.
Conclusion
Moving out on your own and starting your first full-time job is an important step toward financial independence. Along with earning your own income, you will need to keep track of recurring expenses and make sure your bills are paid on time.
The four most common examples of people or companies you might pay regularly using online bill pay are your landlord, electric company, internet provider, and cell phone service provider. Depending on your situation, you may also need to pay a lender, credit card company, or insurance provider.
Online bill payment can make the process simpler by offering convenient scheduling, digital records, and payment reminders. Combine these tools with a realistic budget, regular account reviews, and responsible spending habits.
Your goal is simple: know what you owe, pay it on time, and keep enough money available to cover your expenses. Building these habits early can help you manage your first paycheck with confidence and create a stronger financial foundation for the future.
When Might The 50/30/20 Rule Not Be The Best Saving Strategy To Use?
Sushil Kumar is a results-focused digital marketer specializing in SEO, content planning, and AI-powered workflows. His platform offers easy-to-use AI prompts for creating professional photos.